 Ultimate guide
What Is Commercial General Liability Insurance Coverage?
Quick Summary
Commercial general liability insurance, often called CGL, is a business policy that protects you when someone else claims you caused them harm. It typically pays for third-party bodily injury, property damage, and personal and advertising injury, plus the legal defense costs of those claims.
- Most CGL policies are written on an occurrence basis, covering incidents that happen during the policy period.
- Property damage liability pays when your business damages someone else's property, but not damage to your own property.
- CGL policies generally exclude professional errors, employee injuries, auto accidents, and pollution.
- Check the insurance requirements in your contracts, since limits below those requirements can leave you personally exposed.
- A certificate of insurance summarizes your policy and limits, and clients often request one before letting you work.
Table of Contents
- What Commercial General Liability Insurance Is and How It Works
- What Commercial General Liability Insurance Covers
- Does Commercial General Liability Insurance Cover Property Damage?
- Commercial General Liability Insurance Examples From Real Claim Scenarios
- What Does Commercial General Liability Insurance Not Cover?
- Commercial General Liability Insurance Cost and the Factors That Affect Premiums
- Booking a Coverage Review for Your Everett Business
- Frequently Asked Questions
What Commercial General Liability Insurance Is and How It Works
Last Updated: November 14, 2026
Commercial general liability insurance, often called CGL or general liability, is a business policy that protects you when someone else claims you caused them harm. A CGL policy typically pays for third-party bodily injury, property damage, and personal and advertising injury, along with the legal defense costs that come with those claims.
The policy works by transferring risk. If a customer slips on your floor, a vendor's delivery damages a neighbor's fence, or a competitor claims your advertising infringed on their brand, your policy responds. It pays covered settlements and judgments up to your policy limits and may fund your defense, subject to the terms of your policy.
Occurrence policies versus claims-made policies
Most CGL policies are written on an occurrence basis. An occurrence policy covers an incident that happens during the policy period, regardless of when the claim is reported. If you held a policy in 2025 and a customer is injured in 2025 but sues in 2027, the 2025 policy generally responds.
Claims-made policies work differently. They cover claims that are first reported while the policy is active, so the reporting date matters more than the incident date. Claims-made coverage is more common with professional liability insurance, and it usually requires a retroactive date and continuous coverage to avoid gaps. Readers weighing whether the premium is worth paying can review a cost-benefit analysis of general liability insurance for small business to compare expected protection against what the policy costs. Ask your agent which form your policy uses, because the difference determines whether an old incident is covered.
What Commercial General Liability Insurance Covers
A standard CGL policy is organized around several coverage parts. Understanding them helps you see what protection you actually have.
Bodily injury and property damage liability
Bodily injury liability pays when a third party is physically hurt on your premises or because of your operations. Property damage liability pays when your business damages someone else's property. Both coverages typically include the costs of settlements, judgments, and defense.
Personal and advertising injury
This coverage applies to offenses such as libel, slander, false advertising, copyright infringement in marketing materials, and wrongful eviction. It is one of the most misunderstood parts of a CGL policy, and many business owners assume it covers all online or reputational harm. It does not cover every type of digital dispute, so review the definitions in your policy.
The core coverage parts of a standard CGL policy are summarized below.
| Coverage part | What it pays for | Example from the article |
|---|---|---|
| Bodily injury liability | Third party physically hurt by your business | Customer injured by a loose floor mat |
| Property damage liability | Damage your business causes to others' property | Employee breaks a client's equipment |
| Personal and advertising injury | Libel, slander, false advertising, copyright in marketing, wrongful eviction | Photo used without photographer's permission |
Does Commercial General Liability Insurance Cover Property Damage?
Yes, property damage liability is a core part of most CGL policies. If your employee accidentally breaks a client's equipment during a job, or your delivery truck backs into a neighboring building, the policy can pay to repair or replace the damaged property, plus the defense costs of any resulting claim.
It does not cover damage to your own property. Your building, inventory, and equipment require commercial property insurance. Many small businesses carry both policies, often bundled as a Business Owners Policy (BOP), which combines property, liability, and business interruption protection in one package.
Commercial General Liability Insurance Examples From Real Claim Scenarios
Abstract definitions only go so far, so consider how coverage applies in practice.
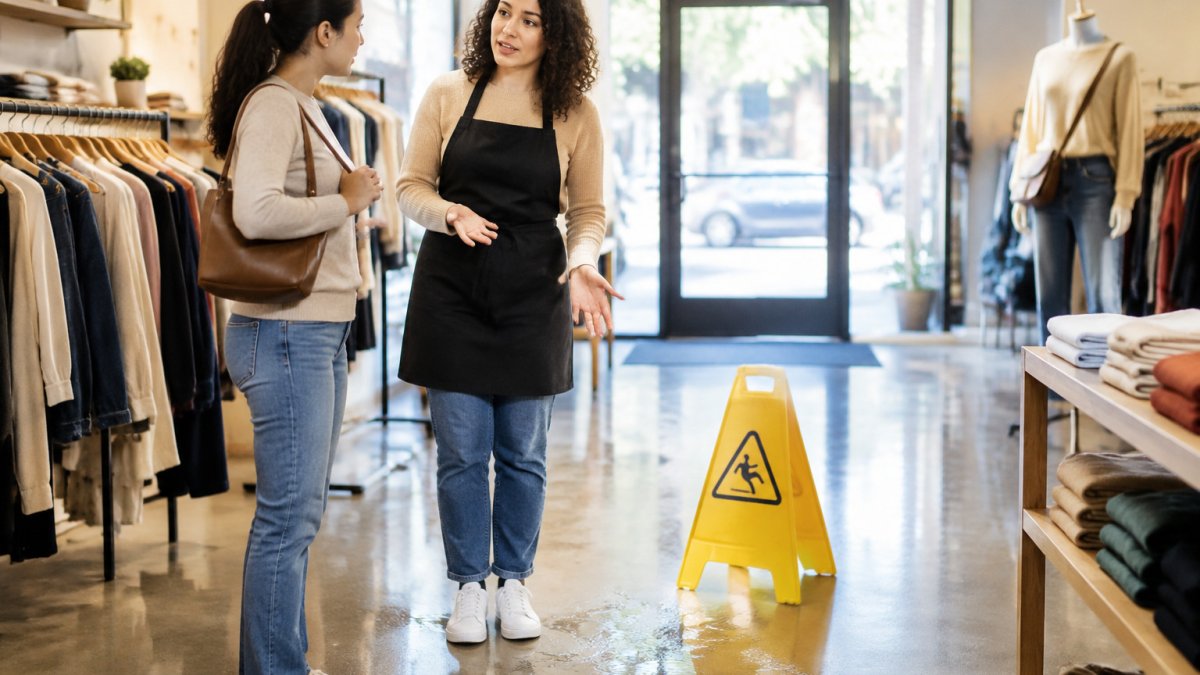
A customer trips over a loose floor mat at a retail shop in Everett and breaks a wrist. The customer's medical bills and any lawsuit settlement fall under bodily injury liability, and the policy pays the defense attorney.
A contractor drops a ladder that dents a client's car parked on the job site. Property damage liability covers the repair.
A small marketing agency uses a photograph in a client campaign without permission from the photographer. The photographer's copyright claim may fall under personal and advertising injury, depending on the policy wording.
Each scenario depends on the exact policy form, endorsements, and limits. Confirm how your policy would respond before assuming a claim will be paid.
What Does Commercial General Liability Insurance Not Cover?
A CGL policy is broad, but it is not a catch-all. The exclusions are where most coverage disputes begin, and understanding them is the difference between assuming you are protected and actually being protected.
Professional errors and faulty workmanship. Claims arising from the rendering of professional services, bad advice, flawed design, an accounting mistake, a missed deadline that costs a client money, are generally excluded.
Employee injuries. Work-related injuries to your own employees fall under workers' compensation, which is a separate policy (Workers' Compensation). CGL responds to third parties, not to your own workforce.
Business autos. Accidents involving vehicles you own, rent, or use in your business require commercial auto coverage.
Pollution. Most CGL forms exclude pollutants, which is why contractors, landscapers, and manufacturers often buy a pollution liability endorsement or a standalone environmental policy.
Damage to your own property. Your building, inventory, tools, and equipment need commercial property insurance.
Intentional acts. Deliberate harm is excluded, and insurers will deny a claim where the injury was expected or intended from the standpoint of the insured.
Employment practices. Claims of wrongful termination, discrimination, or harassment are excluded from CGL and require employment practices liability insurance (EPLI).
Cyber and data breach. Losses from a data breach, ransomware, or network interruption are not covered under a standard CGL form; they require a cyber liability policy or endorsement.
Watch out: The exclusion list is only half the story, the other half is the endorsement schedule attached to your policy, because endorsements can add coverage back or take it away.
Many gaps appear when a business assumes CGL covers everything. For consultants specifically, this page explains which policy covers professional mistakes that general liability leaves out.
Commercial General Liability Insurance Cost and the Factors That Affect Premiums
Premiums vary widely, and pricing depends on your business's underwriting details. Contact Bringas Insurance for a quote tailored to your business. What you can do is understand the mechanics, because CGL pricing is more predictable than it looks once you know what insurers are measuring.
Most small-business CGL policies are rated on exposure, revenue, payroll, square footage, or number of units, multiplied by a rate for your class code. Insurers group businesses into classification codes, and the code is a major driver of the base rate.
How limits change the price. A CGL policy has two limits that matter most: the per-occurrence limit (the most paid for any one claim) and the general aggregate limit (the most paid across the policy term). Limits are typically structured as a per-occurrence limit and a general aggregate limit, and raising the per-occurrence limit generally increases premium by less than a proportional amount. Ask your agent for quotes at the limits you need.
How deductibles change the price. A higher deductible lowers premium, but it shifts the first dollars of every claim onto you.
The other rating factors. Industry and operations, annual revenue or payroll, claims history, location (local litigation patterns and property values), and documented safety practices all feed the rate. A clean loss history and a written safety program can help at renewal, but they rarely overcome a high-risk class code.
Choosing limits against your contracts. The most common under-insurance mistake is buying limits that do not match the contracts you sign. Many commercial leases and client agreements specify required liability limits and may require additional insured status, which extends your policy's protection to the landlord or client for claims arising from your work.
Certificates of insurance. Once coverage is in place, you will be asked to prove it. A certificate of insurance (COI) is a document that summarizes your policy, limits, and additional insured status. Clients, landlords, and general contractors routinely request a COI before letting you work.
To estimate your cost, gather your revenue or payroll figures, a description of your operations, the class code your agent assigns, your claims history, and the insurance requirements from your contracts. Then request a quote and compare policies on coverage terms and limits, not just price.
Booking a Coverage Review for Your Everett Business
Before you buy or renew a CGL policy, have someone review your operations and contracts. A coverage review can identify gaps, check whether your limits match the contracts you sign, and clarify which policy handles which risk. Bringas Insurance can walk you through these questions, and you can request a free quote from Bringas Insurance to see how general liability coverage would apply to your business. Our team can also explain General Liability Insurance options in English for Washington businesses, and if you carry multiple property or liability needs, a Business Owners Policy may be worth comparing.
BUTTON: Request a coverage review CARD_TITLE: Is your business covered for third-party claims? CARD_TEXT: Bringas Insurance helps Everett businesses review liability coverage and request a free quote.
Frequently Asked Questions
What does commercial general liability usually cover?
Commercial general liability insurance usually covers third-party bodily injury and property damage that your business operations cause, along with personal and advertising injury such as libel or copyright infringement in advertising. It also pays for legal defense costs and settlements or judgments up to your policy limits. Coverage applies to claims made by outside parties, not to your own employees' work injuries, which fall under workers' compensation. Policy details vary by insurer, so review your specific policy wording or speak with a licensed agent before relying on any particular protection.
What is not covered by commercial general liability insurance?
Commercial general liability policies typically exclude employee injuries (covered by workers' compensation), damage to your own property, professional errors, auto accidents, pollution, and intentional acts. Many policies also exclude products you have recalled and contractual obligations beyond standard liability. Because exclusions and endorsements differ between carriers, you should read the exclusions section of your policy carefully and ask your agent about gaps, such as professional liability or commercial auto coverage.
Does commercial general liability insurance cover property damage?
Yes, commercial general liability insurance covers third-party property damage that your business operations cause, such as damage to a client's furniture during a job or a customer's vehicle damaged on your premises. It does not cover damage to your own building, equipment or inventory, which requires commercial property insurance. Coverage is subject to your per-occurrence and aggregate limits and any applicable deductible, so confirm those figures with your agent.
How much does commercial general liability insurance cost?
Commercial general liability premiums depend on factors such as your industry and risk class, annual revenue, payroll, claims history, location, coverage limits and deductible. Because pricing depends on these variables, Bringas Insurance does not publish fixed prices. Contact Bringas Insurance for a current quote tailored to your business. Comparing quotes with the same limits and endorsements gives the most accurate picture of cost.
Who needs commercial general liability insurance?
Most small business owners who interact with customers, visit client sites, operate a storefront or sign contracts should consider commercial general liability coverage. Landlords, contractors and service providers often face contractual requirements to carry it. Many clients and landlords ask for a certificate of insurance (COI) as proof of coverage before work begins, so the policy needs to be in force before you submit one.
Can an LLC get general liability insurance?
Yes, an LLC can purchase commercial general liability insurance in its own name. The policy protects the business entity against third-party claims, which helps separate business liability risks from personal assets. Insurance does not replace good business structure or contracts, so it is worth discussing your entity structure and coverage needs together with your agent and attorney.