 How-to
7 Steps to Calculate Total Loss Value for Everett Drivers
Last Updated: November 9, 2026
Quick Summary
Total loss value is calculated by adding the repair cost to the salvage value and comparing that sum to your car's actual cash value (ACV). If repair cost plus salvage value exceeds the ACV, the vehicle is a total loss, and the settlement is based on the ACV, not the repair estimate.
- A car can be repairable in the shop and still be totaled on paper.
- The settlement base is the ACV; the repair estimate only decides whether the car is totaled.
- A $1,000 collision deductible on an $18,000 ACV brings the net payable to $18,800.
- Keeping a $3,000 salvage car reduces the net payable to $15,800 in the example.
- Review the valuation report line by line and dispute errors in writing with evidence.
Table of Contents
- How the Total Loss Formula Sets Your Payout
- How to Use a Car Total Loss Calculator
- Finding the Actual Cash Value of a Totaled Car
- A Total Loss Settlement Calculation You Can Follow
- What Happens When Your Car Is Totaled but Still Drivable
- Reviewing and Disputing the Valuation Report
- Get a Free Quote and Review Your Coverage With Bringas Insurance
- Frequently Asked Questions
How the Total Loss Formula Sets Your Payout
Calculating total loss value for Everett drivers starts with one question: is the repair bill worth more than the car itself? Insurers answer it with a simple formula, and that formula decides what you get paid.
The math looks like this: repair cost + salvage value versus actual cash value (ACV). When the first two numbers add up to more than the ACV, the vehicle is a total loss.
A total loss is a vehicle the insurer will not repair because the cost of fixing it, plus what the wrecked car is worth as scrap, exceeds its pre-loss value. This guide walks you through the steps involved in explaining a settlement to a policyholder.
Here is the key point most drivers miss. The formula compares repair cost plus salvage value to ACV, not repair cost alone. A car can be repairable in the shop and still be totaled on paper.
Repair Cost Plus Salvage Value Versus ACV
Say a collision causes $9,000 in damage. The wrecked car still has $2,000 of salvage value. Together that is $11,000. If the car's ACV is $10,000, the insurer totals it.
Three numbers drive the outcome:
- Repair cost: the shop's written estimate
- Salvage value: what a salvage buyer will pay for the wreck
- ACV: what your car was worth the moment before the crash
Change any one of them and the decision can flip. That is why the valuation report matters so much.
How to Use a Car Total Loss Calculator
A car total loss calculator is a rough screening tool, not an official verdict. It takes your repair estimate, salvage value, and ACV and tells you which side of the line you fall on.
Run it before you accept anything. Here is how:
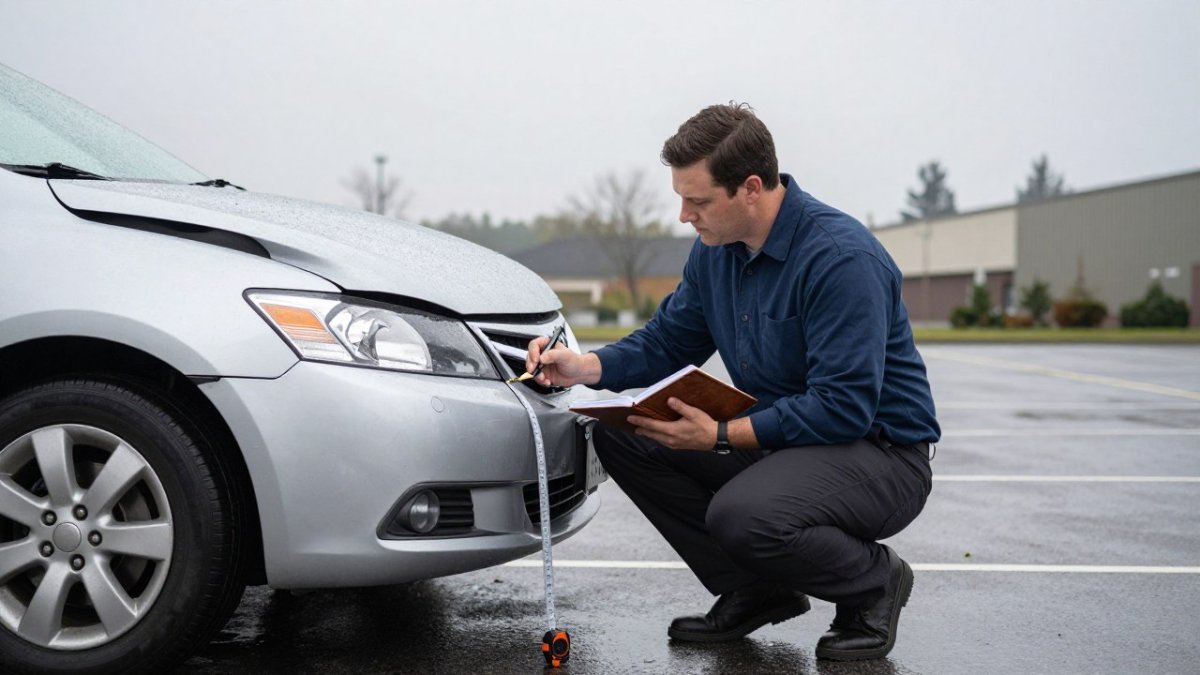
- Get a written repair estimate from a licensed shop.
- Look up your car's private-party value on a pricing guide.
- Ask a salvage yard what the wreck would fetch.
- Enter all three into the calculator.
- Compare the result to your insurer's letter.
If the calculator says "total loss" and your insurer says "repair," ask for the valuation report in writing. Something in their numbers differs from yours, and you have a right to see it.
State rules vary on when an insurer must total a car. Washington applies its own threshold, so check the current rule with the Washington State Office of the Insurance Commissioner rather than assuming a national standard.
Finding the Actual Cash Value of a Totaled Car
The actual cash value of a totaled car is what a willing buyer would have paid for it just before the loss, given its mileage, options, and condition. It is not the price you paid, and it is not the cost of a new replacement.
Adjusters build ACV from comparable vehicles sold or listed nearby. Then they adjust for your car's specifics.
What Adjusters Compare: Mileage, Options, and Condition
Three things move the number most:
- Mileage: lower miles than the comparables raises your value
- Options: trim, packages, and factory features count
- Condition: tires, paint, interior wear, and maintenance records
A common mistake is accepting a valuation built from cars in another region or from the wrong trim level. Those comparables are not really comparable.
If your car is comprehensive or collision covered, the payout comes through that coverage. Our guide on comprehensive vs collision coverage for Washington drivers explains which one applies to a totaled vehicle.
A Total Loss Settlement Calculation You Can Follow
Here is a worked example that follows the money from ACV to the check, using round numbers so the math is easy to track.
Step 1, Confirm the total loss. Pre-loss ACV is $18,000. The repair estimate is $16,000 and salvage value is $3,000. Repair plus salvage is $19,000, which exceeds ACV, so the vehicle totals.
Step 2, Start from ACV, not the repair estimate. The settlement base is the $18,000 ACV. The repair estimate only decides whether the car is totaled; it does not set the payout.
Step 3, Add what your policy allows. Whether applicable sales tax and title or registration fees are added to the ACV depends on your policy and state rules. Confirm the exact treatment in your policy language before you rely on it.
Step 4, Subtract your deductible. A $1,000 collision deductible brings the net payable to $18,800.
Step 5, Subtract any lien payoff. If you still owe $14,000 on the loan, the lender is paid first. The insurer sends $14,000 to the lienholder and the remaining $4,800 to you.
Step 6, Account for salvage if you keep the car. If you retain the vehicle, the insurer subtracts the salvage value from the settlement.
Watch out: the ACV offer and the check you deposit are rarely the same number. Taxes and fees may be added, while the deductible, lien payoff, and retained-salvage value come out first.
The worked example follows the money from ACV to the check in six steps.
| Step | Action | Amount in example |
|---|---|---|
| 1 | Confirm the total loss | $16,000 repair + $3,000 salvage vs $18,000 ACV |
| 2 | Start from ACV, not repair estimate | $18,000 settlement base |
| 3 | Add what your policy allows | Sales tax and title or registration fees |
| 4 | Subtract your deductible | $1,000 collision deductible brings net to $18,800 |
| 5 | Subtract any lien payoff | $14,000 to lender, $4,800 to you |
| 6 | Account for salvage if you keep the car | $3,000 salvage reduces net payable to $15,800 |
What Happens When Your Car Is Totaled but Still Drivable
A drivable car can still be a total loss. If the repair math crosses the threshold, the insurer totals it even when it rolls into the driveway.
What happens next depends on your state's salvage rules. You may be able to keep the car under a retained salvage arrangement, where the salvage value is subtracted from your payout and you handle repairs yourself.
That path has a catch. The car may need a salvage title or rebuilt title, and some lenders will not finance a rebuilt vehicle.
Ask two questions before you decide:
- What will my insurer pay if I keep the car?
- What title brand will my state apply?
If you still owe more than the ACV, gap coverage may cover the difference. Our article on whether gap insurance is worth it for used cars covers when that protection pays out.
Reviewing and Disputing the Valuation Report
Review the valuation report line by line before you sign anything. Errors in trim, mileage, options, or condition are common, and each one lowers your offer. The goal is to find the specific comparables the adjuster used and show why they do not match your car.
Audit the comparables, not just the total. For each comparable vehicle listed, check:
- Trim and drivetrain match your car exactly (for example, a base model versus a sport trim, or front-wheel drive versus all-wheel drive)
- Mileage is within a reasonable band of yours, and the adjustment math is shown
- Options you paid for are listed (packages, tow equipment, sunroof, upgraded wheels)
- Condition reflects your maintenance records, tires, and interior wear
- Market is local, comparables from another region may carry different pricing
Document corrections with evidence. Pull your window sticker or VIN decode, maintenance receipts, photos of options and condition, and current local listings for similar vehicles. Send a written correction request to the adjuster that lists each error, the supporting document, and the dollar impact you believe it has. Keep a copy of everything.
Use the appraisal clause if the insurer will not move. Many auto policies include an appraisal provision that lets you and the insurer each hire an independent appraiser, with a neutral umpire if they disagree. Ask your adjuster whether your policy has one and follow its written steps.
Know the state timeline. Claim-handling deadlines and total-loss rules are set at the state level, so confirm the current requirements with the Washington State Office of the Insurance Commissioner rather than assuming a national standard. If weeks pass without a substantive response, escalate in writing and keep a dated log of every call and email.
If the numbers look wrong, dispute in writing. Ask for the comparables used and the adjustment method. If the insurer will not move, an independent appraisal is the next step, and many policies include an appraisal clause for exactly this.
Do not let a stalled claim sit. If weeks pass without a real answer, our guide on what to do if your insurance claim is delayed lays out the escalation path.
Get a Free Quote and Review Your Coverage With Bringas Insurance
The formula is simple. The settlement is where drivers lose money, usually because they never checked their coverage before the crash.
At Bringas Insurance, we offer insurance solutions for auto, home, life, and business, and we provide free quotes.
You can request a free quote from Bringas Insurance and see how your current policy stacks up. Ask us about Bringas Insurance coverage options for your vehicle and your family.
Get started with Bringas Insurance and review your auto coverage with a clear picture of what your policy actually pays.
A total loss claim rewards the driver who checks the math. Pull your policy, confirm your coverage, and get a second set of eyes on the valuation before you sign. Bringas Insurance offers free quotes, bilingual guidance for Everett families, and coverage for auto, home, life, and business under one roof. Get started with Bringas Insurance and know where you stand before the next claim.
Frequently Asked Questions
How is total loss value calculated?
Insurers compare two numbers: the cost to repair your vehicle and its actual cash value (ACV) before the accident. The common total loss formula adds the repair estimate to the salvage value. If that total meets or exceeds the ACV, the vehicle is declared a total loss. Your settlement is then based on the ACV, minus your deductible and any loan or lease payoff owed to a lienholder, not on the repair estimate itself.
What should I do if I disagree with my total loss valuation?
Ask for the valuation report and check the comparable vehicles it lists. Look for wrong trim levels, missing options, higher mileage than your car actually has, or comparables from outside your market. Send the adjuster documentation such as maintenance records, recent upgrades, and independent appraisal results. If the gap remains, you can request an independent appraisal and escalate the dispute through your insurer's formal process or your state insurance regulator.
Can I keep a car that is declared a total loss?
In many cases yes, through owner-retained salvage. The insurer deducts the salvage value from your settlement and you keep the vehicle, but you will typically need to apply for a salvage title and meet your state's inspection and repair requirements before it can be driven again. Confirm the rules with your state's motor vehicle licensing agency before you agree, and weigh the payout reduction against repair costs.
What happens when your car is totaled but still drivable?
A drivable vehicle can still be a total loss if the repair estimate plus salvage value meets the ACV threshold. The insurer settles based on value, not drivability. You may be able to keep driving it temporarily, but confirm coverage and rental or loss-of-use terms with your adjuster first. If you retain the salvage, the vehicle usually needs a salvage title and repairs before it is legal to drive.